Protect your home, your family, and the legacy you leave behind.
Mortgage protection, final expense, Medicare, and cash value life insurance, explained in plain English. I compare multiple carriers for you, so you get a plan that fits instead of a sales pitch.
Coverage for every stage of life
Whether you just bought a home, want to spare your family the cost of a funeral, or are sorting out Medicare, you get one point of contact and honest answers.
Mortgage Protection
Life insurance designed to pay off or keep paying your mortgage if you pass away, so your family keeps the house.
Learn more →Final Expense
Smaller whole life policies that cover funeral costs, medical bills, and final debts, often with simple health questions.
Learn more →Medicare
Turning 65 or reviewing your plan? Get help comparing Medicare Advantage, Supplements, and drug plans.
Learn more →Your family keeps the house, no matter what.
Your mortgage is likely your biggest monthly bill. Mortgage protection is life insurance sized to your home loan, paid directly to your family, not the bank, so they decide how to use it.
- Coverage amount and length matched to your mortgage balance and term
- Benefit is paid to your beneficiaries, who can pay off the loan or keep making payments
- Many policies offer living benefit riders that may let you access part of the benefit early if you're diagnosed with a qualifying terminal, chronic, or critical illness
- Optional return-of-premium designs are available with some carriers
Who it's for
- New homeowners
- Lock in coverage while you're younger and rates are lower.
- Single-income households
- If one paycheck covers the mortgage, that income needs protecting.
- Parents with young kids
- Keep the kids in the same home and school if the worst happens.
Rider availability, cost, and qualifying conditions vary by carrier, product, and state. Accelerated benefits reduce the death benefit paid to beneficiaries.
The details
- Typical coverage
- Smaller face amounts, commonly from about $5,000 to $50,000, depending on the carrier.
- Underwriting
- Many plans use a short health questionnaire instead of a medical exam. Graded or guaranteed-issue options exist for some health histories, but they usually include a waiting period.
- Premiums
- Whole life premiums are generally level for life and the policy doesn't expire as long as premiums are paid.
Don't leave your family with the bill.
Funerals, medical bills, and final debts can cost families thousands of dollars at the hardest possible moment. Final expense insurance is a small whole life policy built to cover those costs.
- Benefit paid directly to your beneficiary, usually within days to weeks of a claim
- Your family decides how to use it: funeral, burial, medical bills, or debts
- Designed for adults roughly 50 to 85, with options for many health conditions
Medicare, without the confusion.
Between Parts A, B, C, and D, Supplements, and enrollment deadlines, Medicare is easy to get wrong. I'll walk you through your options and help you compare plans available in your area.
- Turning 65: understand your Initial Enrollment Period and avoid late-enrollment penalties
- Medicare Advantage vs. Medicare Supplement: compare costs, networks, and coverage side by side
- Prescription drug coverage: check that your medications and pharmacies are covered
- Annual review: plans change every year, so it pays to re-check during the Annual Enrollment Period (Oct 15 to Dec 7)
What to have ready
- Your Medicare card
- Or your expected Part A and B start dates if you're new.
- Your doctors
- So we can check which plans include them.
- Your prescriptions
- Names and dosages, to compare drug costs.
We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov, 1-800-MEDICARE (TTY 1-877-486-2048), or your local State Health Insurance Assistance Program (SHIP) to get information on all of your options. Not connected with or endorsed by the U.S. government or the federal Medicare program.
Build a family bank with permanent life insurance.
Wealthy families have long used permanent life insurance to store wealth, access cash, and pass money to the next generation. The idea, often called the Rockefeller Method or Infinite Banking, is to use a properly structured cash value policy as your own private source of capital.
1. Fund the policy
You pay premiums into a permanent policy, typically dividend-paying whole life, designed to build cash value efficiently rather than maximize the death benefit.
2. Access your cash value
Once cash value builds, you can borrow against it for things like a car, a business, or an emergency, without a credit check and on your own repayment schedule.
3. Pass it on
The death benefit goes to your family, generally income-tax-free, so the wealth you built continues after you.
The honest part
This strategy works best for disciplined savers with a long time horizon. Before you start, you should know:
- Cash value builds slowly in the early years. Expect it to take several years before it's a meaningful source of funds.
- Policy loans charge interest. Unpaid loans and interest reduce your cash value and death benefit.
- Surrendering a policy early can mean getting back less than you paid in.
- Over-funding a policy beyond IRS limits can turn it into a Modified Endowment Contract, which changes how withdrawals and loans are taxed.
- Life insurance is not a bank account or an investment. Dividends are not guaranteed.
If it fits your goals, I'll show you a real carrier illustration, including guaranteed and non-guaranteed values, before you commit to anything.
See If It Fits YouThree simple steps
Book a free call
Pick a time that works for you. It takes about 20 to 30 minutes, by phone or video.
We compare options
I'll learn your goals and budget, then compare plans from multiple carriers you qualify for.
You decide
No pressure. If a plan makes sense, I'll handle the application and stay with you after it's approved.
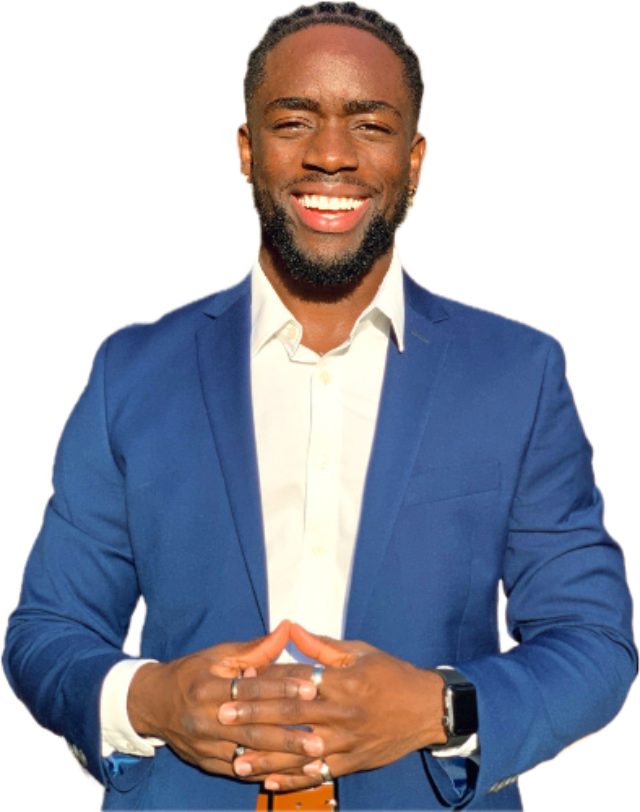
Hi, I'm Schweivensky Metellus.
I'm an independent licensed insurance agent based in Florida. Because I'm not captive to one company, my job is to find the coverage that actually fits your family and your budget, then explain it so you understand exactly what you're buying.
My clients are homeowners, parents, retirees, and people turning 65 who want straight answers. I'd rather tell you a policy isn't right for you than sell you something you don't need.
Frequently asked questions
Does it cost anything to talk with you?
No. Consultations are free and there's no obligation to buy anything.
How do you get paid?
Like most insurance agents, I'm paid a commission by the insurance company when a policy is issued. You don't pay me separately, and the premium is set by the carrier, not by me. Because I work with multiple carriers, I'm free to recommend the one that fits you best.
Will I need a medical exam?
It depends on the product, your age, and the coverage amount. Many final expense and some mortgage protection policies use health questions only. Larger policies may require an exam, which is usually free and done at your home.
Can you help if I have health problems?
Often, yes. Carriers look at health differently, so a condition that gets declined by one company may be accepted by another. Being independent lets me shop around.
Is the Rockefeller Method right for everyone?
No. It works best for people with steady income who can commit to funding a policy for many years. If you need coverage on a tight budget, term or final expense insurance is usually a better starting point.
Do you sell Medicare plans in my area?
Plan availability depends on your county. Book a call and I'll check which plans I can offer where you live, and point you to Medicare.gov for the full list of options.
Book your free call
Choose a time below, or call or text me directly.